How an Extra $200 a Month Affects Your Mortgage (Real Numbers)
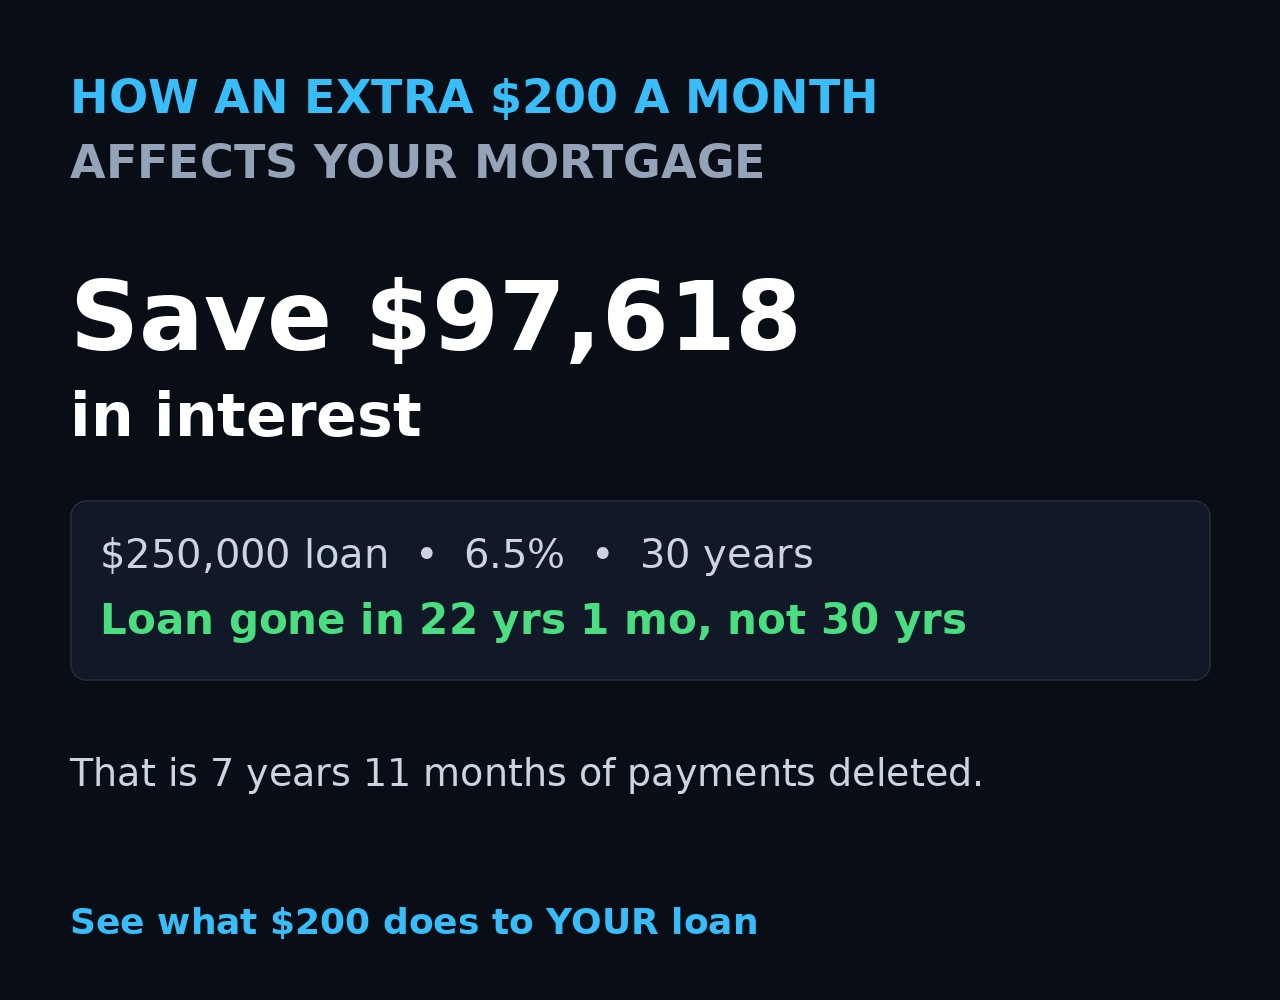
Short answer: on a typical mortgage, an extra $200 a month is worth far more than $200. On a $250,000 loan at 6.5%, it pays the loan off 7 years and 11 months early and saves $97,618 in interest. Here is exactly how that happens, with the real numbers for several loan sizes and extra amounts.
The Exact Effect of an Extra $200/Month ($250,000 Loan
at 6.5%)
| Metric | No Extra Payment | With +$200/Month | Difference |
|---|---|---|---|
| Monthly payment (P&I) | $1,580.17 | $1,780.17 | +$200 |
| Loan paid off | 360 months (30 yrs) | 265 months (22 yrs 1 mo) | 95 months sooner |
| Total interest | $318,861 | $221,243 | $97,618 saved |
Notice the exchange rate: over the life of this loan, every $1 of extra principal you pay returns about $1.84 in interest savings — because each extra dollar of principal deletes interest that would have been charged on it again and again for decades.
Why $200 Has Such a Big Effect: Your First Payment Explains It
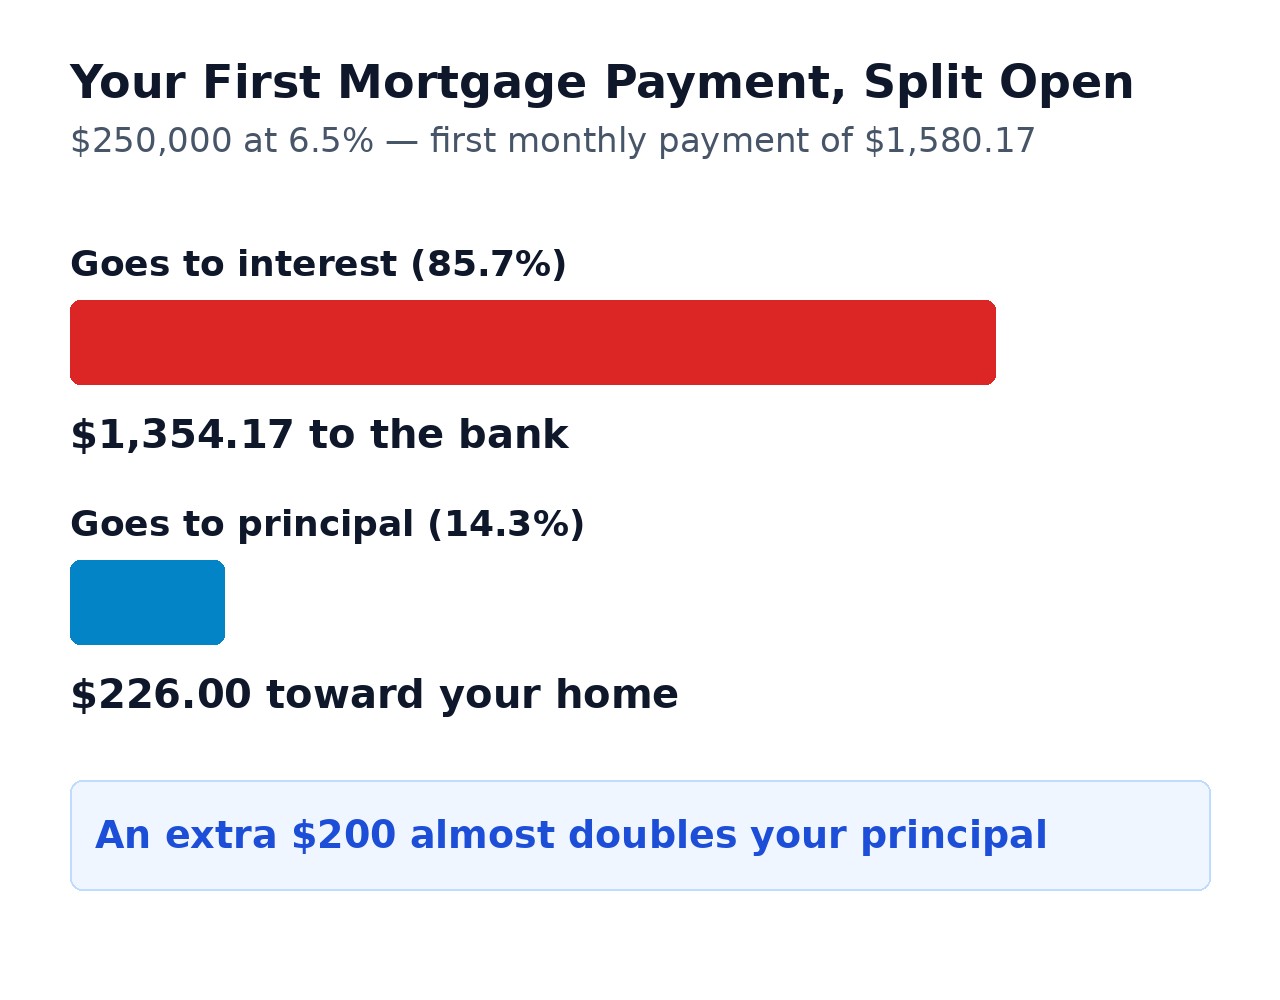
Mortgage interest is charged each month on your remaining balance. At the start of a $250,000 loan at 6.5%, your first $1,580.17 payment splits like this:
- $1,354.17 goes to interest (85.7% of the payment)
- Only $226.00 goes to principal
That is why extra principal is so powerful early on. An extra $200 almost doubles the principal paid in your first month — and every dollar of balance you remove in year 1 would otherwise be charged interest for up to 29 more years.
What If You Pay a Different Amount Extra?
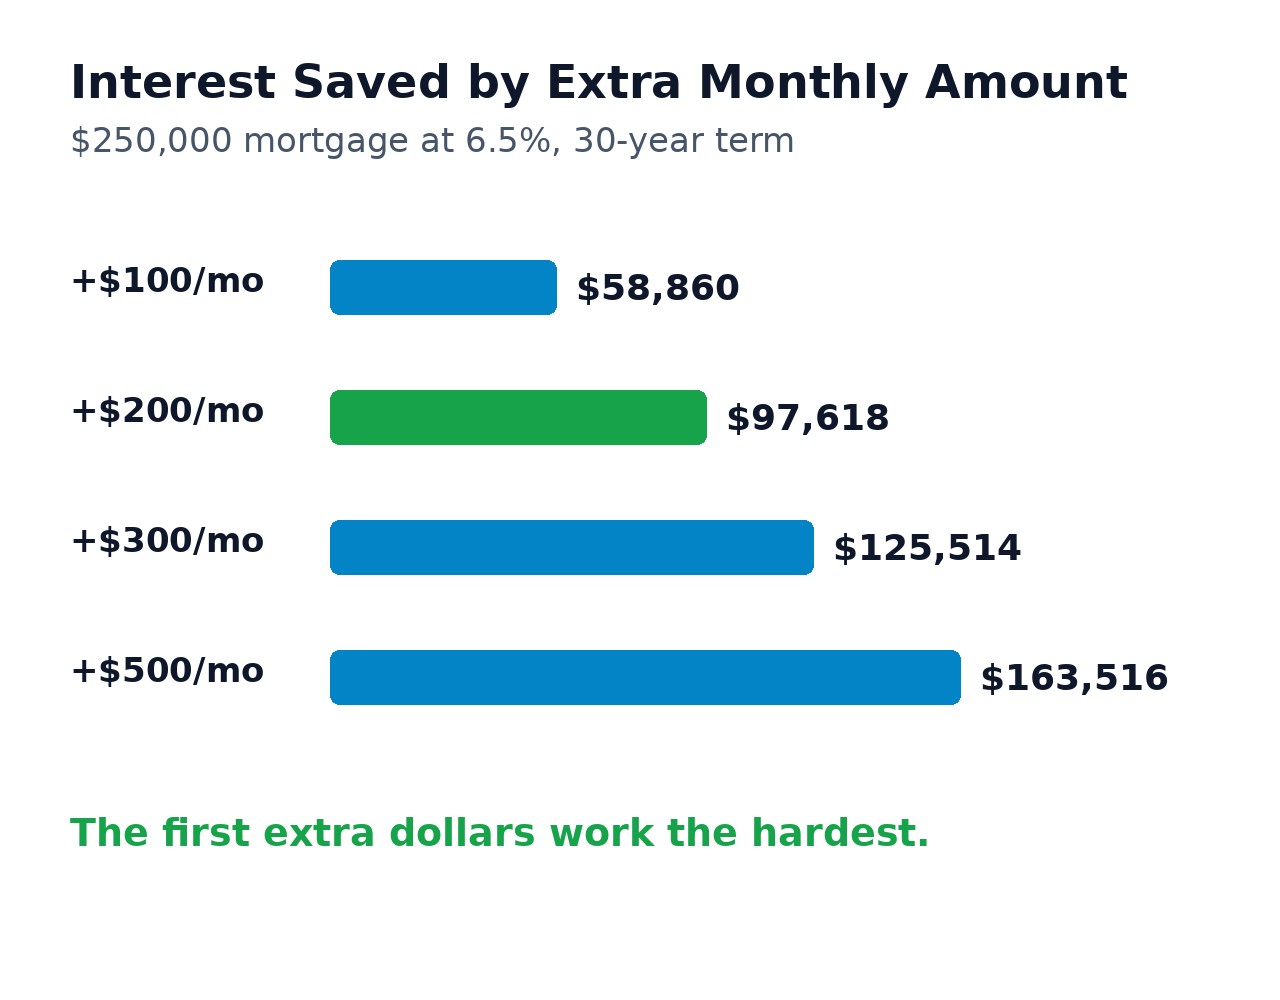
Same loan — $250,000 at 6.5% for 30 years. Watch how the savings scale:
| Extra per Month | Paid Off In | Total Interest | Interest Saved | Time Saved |
|---|---|---|---|---|
| $0 | 30 yrs 0 mos | $318,861 | - | - |
| +$100 | 25 yrs 4 mos | $260,001 | $58,860 | 4 yrs 8 mos |
| +$200 | 22 yrs 1 mo | $221,243 | $97,618 | 7 yrs 11 mos |
| +$300 | 19 yrs 8 mos | $193,347 | $125,514 | 10 yrs 4 mos |
| +$500 | 16 yrs 3 mos | $155,345 | $163,516 | 13 yrs 9 mos |
Two lessons from the table: even $100 a month saves $58,860, and the first extra dollars are the most valuable ones — the gain from $0 to $100 is bigger per dollar than from $300 to $500.
An Extra $200/Month on Other Loan Sizes
| Loan | Monthly (P&I) | Paid Off With +$200 | Interest Saved | Time Saved |
|---|---|---|---|---|
| $150,000 at 6%, 30 yrs | $899.33 | 19 yrs 2 mos | $71,063 | 10 yrs 10 mos |
| $250,000 at 6.5%, 30 yrs | $1,580.17 | 22 yrs 1 mo | $97,618 | 7 yrs 11 mos |
| $350,000 at 7%, 30 yrs | $2,328.56 | 23 yrs 8 mos | $122,122 | 6 yrs 4 mos |
The higher your rate, the more each extra dollar saves you — on the $350,000 loan at 7%, the same $200 a month saves over $122,000.
Try It With Your Own Loan
Enter your exact loan below — the calculator shows your interest saved, time saved, payoff time, chart and full amortization schedule instantly:
Loan Parameters
Extra Payments
| Period | Payment | Principal | Extra | Interest | Balance |
|---|
How to Make the Extra $200 Count (3 Rules)
- Say "principal only": tell your servicer — in the payment portal or in writing — to apply the extra to principal. Otherwise some servicers hold it toward next month's payment, which saves you almost nothing.
- Check for a prepayment penalty: most modern mortgages have none, but confirm before you start. One call to your servicer settles it.
- Start now, not "someday": extra payments in the early years are worth several times the same payment later, because the balance — and the interest charged on it — is at its largest today.
Frequently Asked Questions
1. Is paying an extra $200 a month worth it?
Mathematically, on a $250,000 mortgage at 6.5% it removes $97,618 of interest and almost 8 years of payments. Whether it is the best use of your money depends on your other debts, emergency savings and your loan's rate — the calculator above shows what it does to the mortgage itself.
2. Does the extra $200 go to principal automatically?
Not always. Many servicers apply extra money to principal by default, but some apply it to the next month's payment unless you instruct them otherwise. Select "principal only" in your payment portal or note it on the payment.
3. What if I can only afford an extra $100 a month?
On the same $250,000 loan at 6.5%, an extra $100 a month still saves $58,860 and pays the loan off 4 years and 8 months early. Smaller amounts started earlier usually beat larger amounts started later.
4. Is one yearly lump sum as good as $200 every month?
Close, but monthly wins slightly: $200 leaving your account each month cuts the balance earlier on average than $2,400 once a year. You can model both in the calculator — it accepts monthly extras, an annual lump sum, and one-time payments.
Want the full picture — balance chart, year-by-year schedule and every payoff scenario in one place? Use the main mortgage payoff calculator with extra payments and test your own numbers.