Biweekly vs Monthly Extra Mortgage Payments: Which Pays Off Faster?
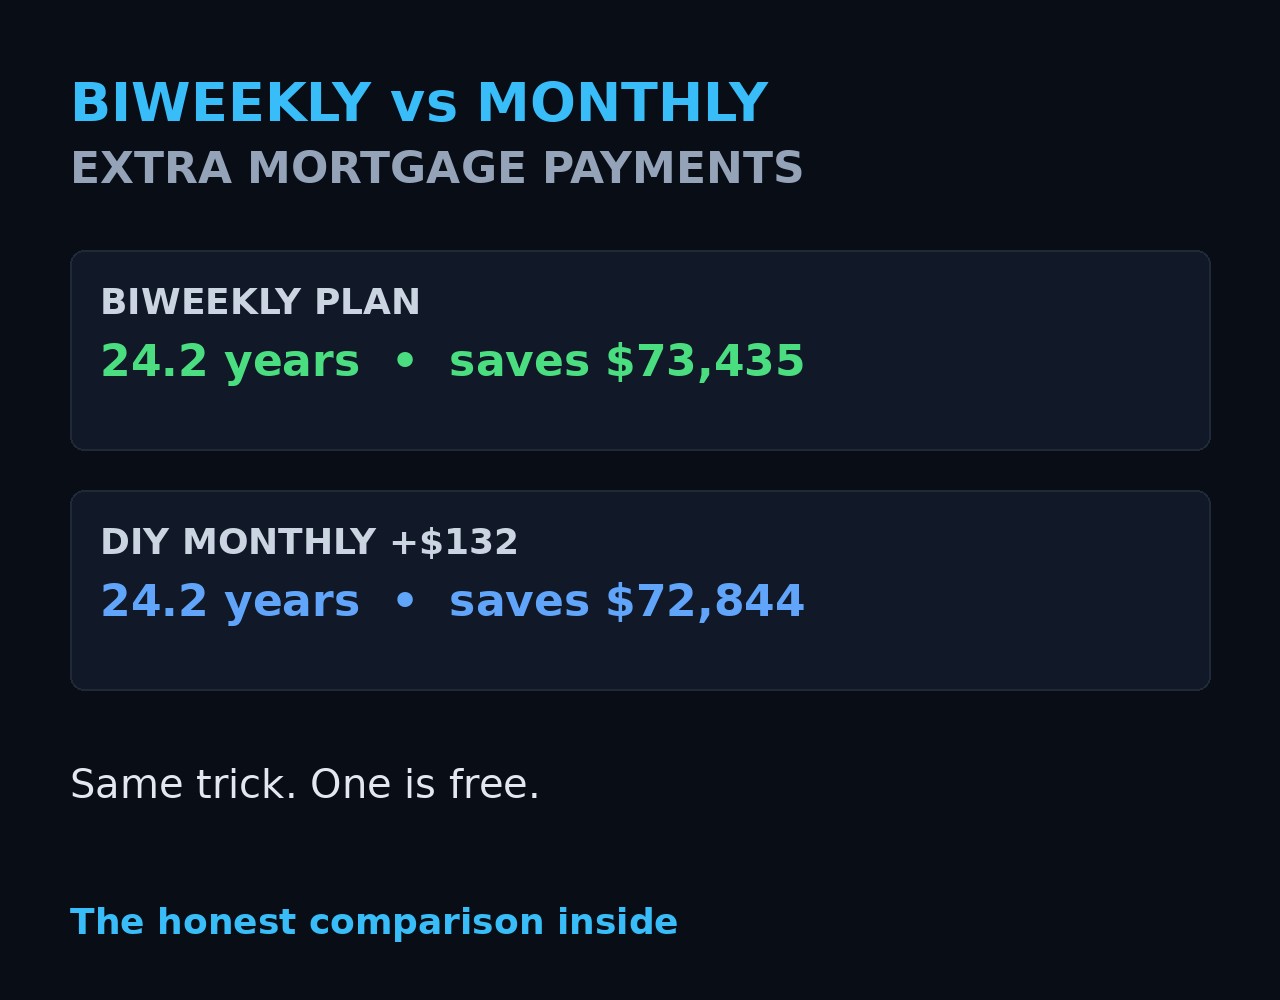
Biweekly payments have a great reputation — but the magic is not in the schedule, it is in one hidden extra payment. Here is the honest comparison on a $250,000 loan at 6.5%: biweekly finishes in 24.2 years and saves $73,435… and simply adding $132 a month yourself finishes in 24.2 years and saves $72,844 — with no program, no fees and no third party touching your money.
How Biweekly Payments Actually Work
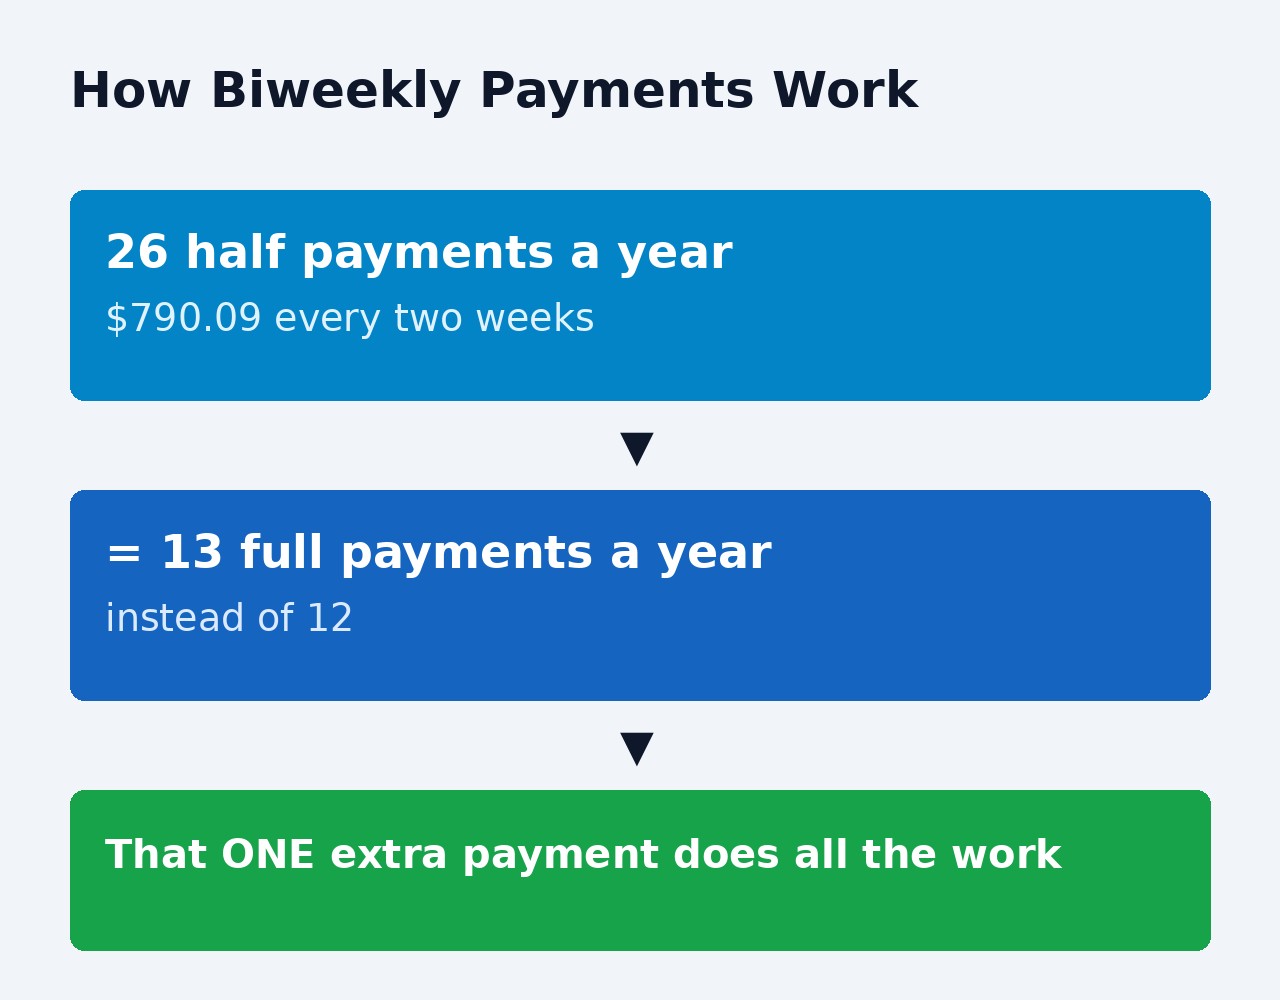
A biweekly plan takes half your monthly payment every two weeks — $790.09 on this loan. There are 26 two-week periods in a year, so you make 26 half payments = 13 full payments a year instead of 12. That one "invisible" extra payment is the entire trick. Biweekly is not a special rate or a lender discount; it is a packaging of one extra payment per year.
The Head-to-Head Numbers
| Method | You Pay | Paid Off In | Total Interest | Interest Saved |
|---|---|---|---|---|
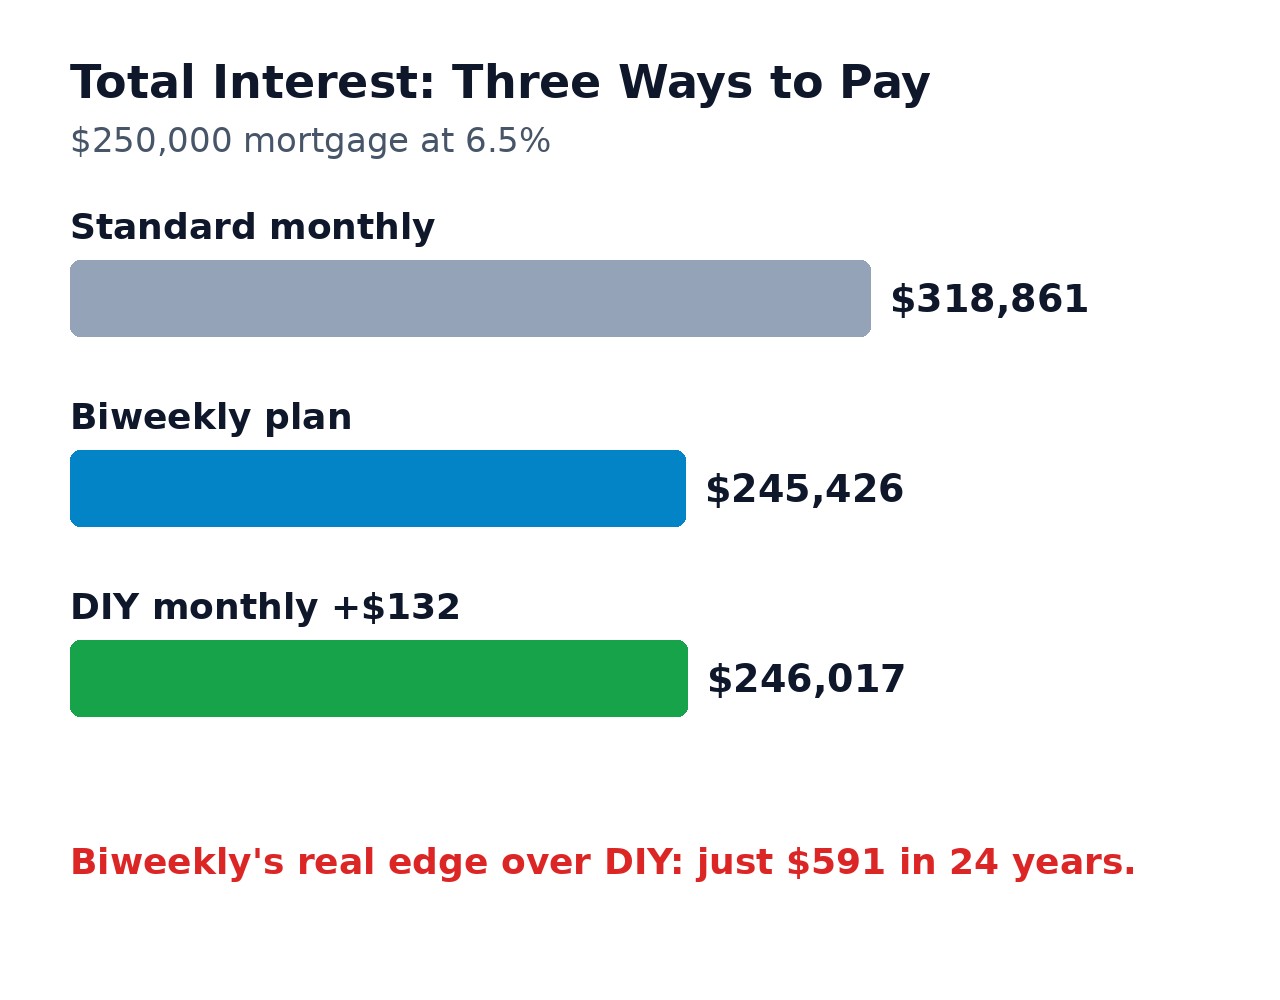
| Standard monthly | $1,580.17 / month | 30.0 years | $318,861 | - |
| Biweekly plan | $790.09 every 2 weeks | 24.2 years | $245,426 | $73,435 |
| DIY monthly extra | $1,580.17 + $132 extra / month | 24.2 years | $246,017 | $72,844 |
The biweekly plan's edge is exactly $591 over 24 years — because its payments land a little earlier in the month on average. That tiny edge is real, but it is the first thing a program fee eats.
The Fee Trap (Read This Before Joining Any Biweekly Program)
- Third-party biweekly programs charge setup fees (often $200-$400) plus monthly service fees. At even $8/month, fees over 24 years pass $2,300 — nearly four times the plan's $591 natural edge.
- Many servicers do not credit half payments. They hold your first biweekly half until the second arrives, then apply one monthly payment — so the money sits idle and the only real acceleration is still just the 13th payment.
- The DIY version is identical in effect and free: divide one monthly payment by 12 ($132 here) and add it to every monthly payment as principal. Same 13th payment, zero fees, full control, pause any time.
Model the DIY Biweekly Yourself
The calculator is pre-set with the DIY biweekly equivalent — one extra payment a year, spread monthly ($132). Try your own loan, or push further: the extra $200 a month version of this plan finishes the same loan in just 22.1 years:
Loan Parameters
Extra Payments
| Period | Payment | Principal | Extra | Interest | Balance |
|---|
See every payment laid out in the amortization schedule with extra payments, or test bigger scenarios in the main mortgage payoff calculator with extra payments.
Frequently Asked Questions
1. Do biweekly payments really save money?
Yes — about $73,435 on a $250,000 loan at 6.5%, finishing roughly 5.8 years early. But the saving comes from making 13 payments a year instead of 12, not from the two-week rhythm itself.
2. Is biweekly better than paying extra monthly?
Barely: about $591 better over 24 years on the example loan, because payments land slightly earlier. Any program fee larger than that makes monthly DIY the winner — and monthly DIY is free and pausable.
3. How do I do biweekly myself without a program?
Take your monthly principal-and-interest payment, divide by 12, and add that amount as extra principal to every monthly payment ($1,580.17 ÷ 12 = $132). Mark it "principal only". You have replicated the biweekly plan exactly.
4. My lender offers a free biweekly option. Should I take it?
If it is genuinely free and the servicer credits each half payment immediately (ask both questions directly), it is a fine, automatic way to make the 13th payment. If either answer is no, the DIY monthly extra gives you the same result without the drawbacks.